What Should Buyers Know About Flood Zones Before Purchasing a Home?
TL;DR
Flood zones can affect more than where water may reach a property. They can influence flood insurance costs, mortgage requirements, property expenses, and how you plan for future ownership. Before buying a home in Rhode Island, Massachusetts, or Connecticut, buyers should review the property's flood zone, insurance requirements, elevation information, and potential risks rather than relying only on what the property looks like today.
What Is a Flood Zone and Why Does It Matter?
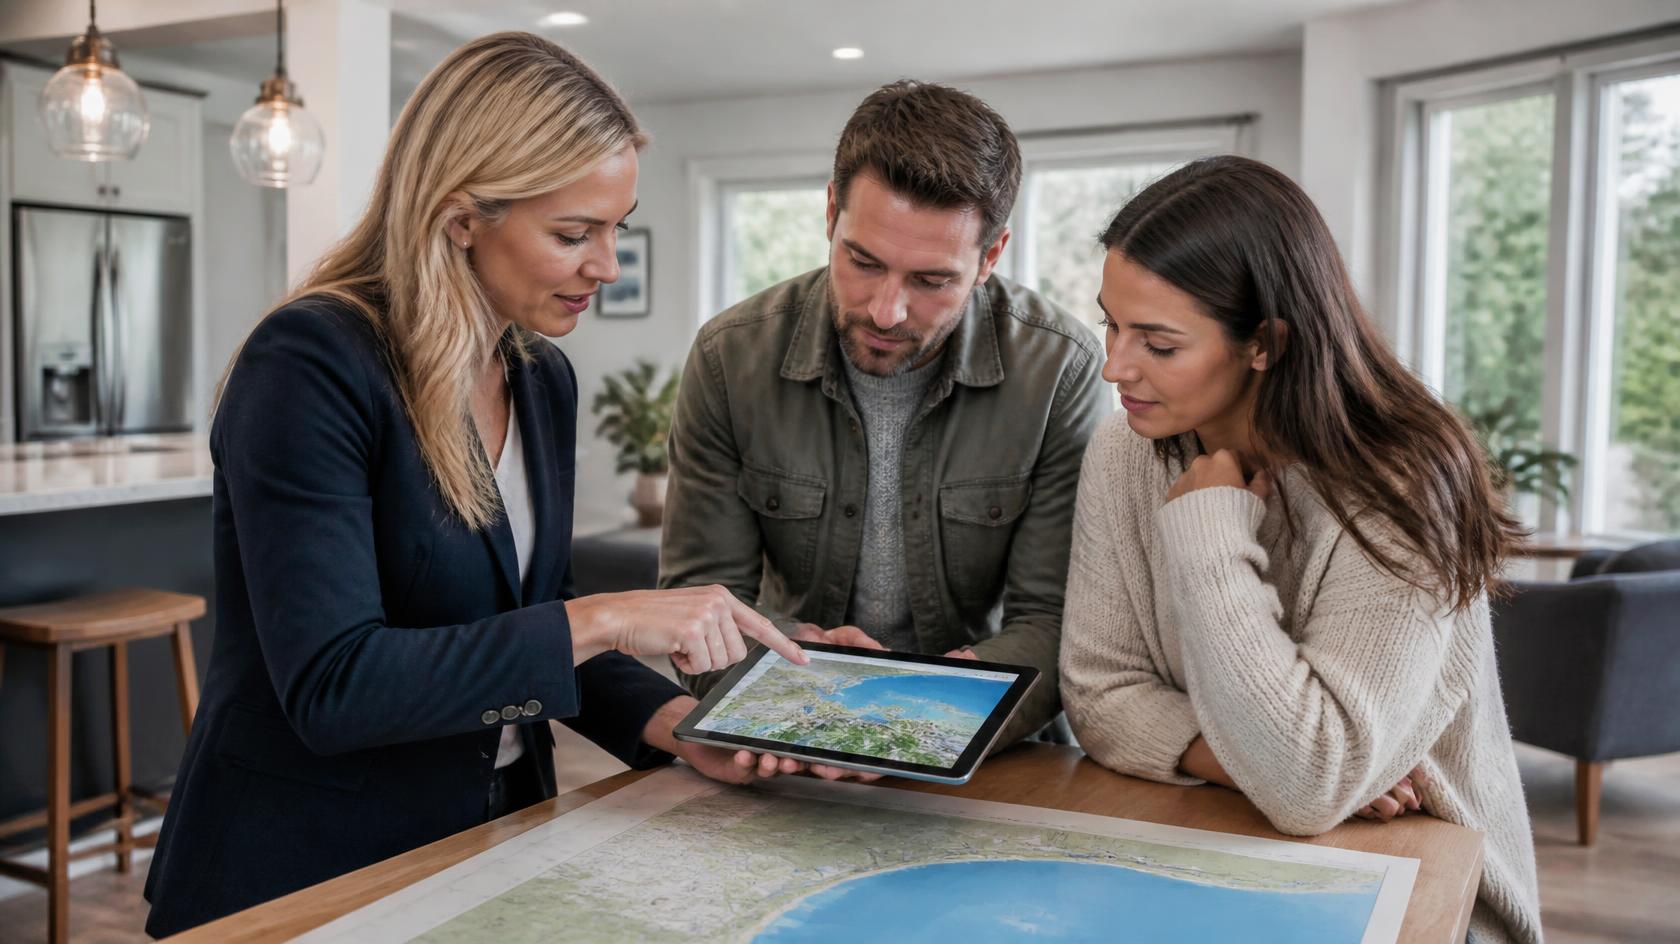
A flood zone is a geographic area that has been classified according to its potential flood risk. The Federal Emergency Management Agency (FEMA) uses flood maps to identify areas with different levels of flood risk.
One important point for buyers is that being outside a high-risk flood zone does not necessarily mean a property can never flood. Flooding can happen for different reasons, including heavy rainfall, drainage problems, coastal storms, rivers, and other weather events.
This matters particularly in New England. Rhode Island, Massachusetts, and Connecticut have coastal communities, rivers, streams, wetlands, and low-lying areas where flood risk can vary considerably from one property to another.
A buyer shouldn't assume that two homes only a few streets apart have the same flood exposure. The property's specific location matters.
Before making an offer, buyers should investigate the property's current flood-zone designation and understand what that designation could mean for ownership costs and insurance.
How Flood Zones Can Affect Your Mortgage and Insurance
One of the biggest financial considerations is flood insurance.
If a property is located in a high-risk flood area and the mortgage lender requires flood insurance, that insurance becomes an additional cost that should be included in the buyer's housing budget.
This can make an important difference when comparing homes.
A property might initially appear affordable based on its purchase price and estimated mortgage payment, but the overall monthly housing cost could be higher once insurance and other property-specific expenses are considered.
Flood insurance is also different from standard homeowners insurance. A typical homeowners policy generally does not cover flood damage, so buyers should understand exactly what protection is available and whether additional flood insurance is appropriate or required.
Before purchasing, ask an insurance professional for an actual quote rather than relying on a general estimate. Insurance costs can vary depending on the property's location, construction, elevation, coverage, deductible, and other factors.
The earlier you obtain that information, the easier it is to evaluate the home's true cost.
Don't Rely Only on a FEMA Flood Map
FEMA flood maps are an important starting point, but buyers should look at more than a single map classification when evaluating a property.
A property's flood risk can involve factors that aren't immediately obvious from standing in the yard or walking through the house. A home may look perfectly dry during a showing while still having a history of water intrusion or being vulnerable to specific weather conditions.
Buyers should consider asking about:
- Previous flooding or water intrusion
- Basement or crawl-space water
- Drainage around the property
- Sump pumps and drainage systems
- Previous insurance claims, when information is available
- Elevation information
- Nearby rivers, streams, wetlands, or coastal areas
- Flood-resistant improvements
- The property's flood insurance history when available
For properties where flood exposure is a significant concern, buyers may also want to consult professionals who can provide more detailed information about elevation, drainage, insurance, or engineering considerations.
The goal isn't to automatically eliminate every home located in or near a flood-risk area. It's to understand the risk before committing to the purchase.
What Buyers Should Ask Before Making an Offer
If you're considering a home that may have flood exposure, asking questions early can prevent unpleasant surprises later.
Start by asking your real estate professional about the property's flood-zone designation and available property disclosures. Your lender can explain whether the loan will require flood insurance, while an insurance professional can provide an estimate of the actual cost.
You should also review the property carefully during the inspection period.
Pay particular attention to basements, foundations, walls, floors, mechanical systems, and areas where water could enter or collect. Signs of previous moisture, staining, mold, damaged materials, or drainage problems may warrant additional investigation.
If the property has a basement, ask specifically about previous water issues and how the property handles heavy rain.
It's also important to understand that flood risk can change over time. Weather patterns, development, drainage improvements, coastal conditions, and updates to flood maps can all affect how buyers and insurers evaluate a property.
Doing this research before closing gives you more information when deciding whether the home is right for you.
How Flood Risk Should Factor Into Your Home-Buying Decision
A flood-zone designation doesn't automatically mean a home is a bad investment or that you shouldn't buy it. For some buyers, the property may have features, location, price, or other benefits that make the additional risk manageable.
The important question is whether you understand the total cost and responsibility of ownership.
Before purchasing, consider the purchase price, mortgage payment, property taxes, homeowners insurance, potential flood insurance, maintenance, and any improvements needed to protect the property.
You should also think about resale. Future buyers will likely have many of the same questions about flood risk, insurance, and costs that you're asking today.
If you understand the risks, obtain appropriate insurance, complete your due diligence, and feel comfortable with the property's overall financial picture, a home in a flood-risk area may still be worth considering.
The key is not to discover the flood-related costs after you've already purchased the home.
Frequently Asked Questions
How do I know if a house is in a flood zone?
Buyers can review FEMA flood maps and discuss the property's designation with their real estate professional, lender, and insurance provider. A property's specific location should be evaluated rather than relying on general information about the surrounding community.
Do I need flood insurance if my home is in a flood zone?
Depending on the property's flood-risk designation and your mortgage lender's requirements, flood insurance may be required. Even when it isn't mandatory, buyers may still want to consider coverage based on the property's actual risk.
Does homeowners insurance cover flooding?
Standard homeowners insurance generally does not cover flood damage. Buyers should speak with an insurance professional about available flood coverage and the specific risks associated with the property.
Can a house outside a high-risk flood zone still flood?
Yes. Flood risk isn't limited to properties in designated high-risk areas. Heavy rainfall, drainage problems, storms, rivers, and other conditions can cause flooding in areas with different flood classifications.
Should I avoid buying a house in a flood zone?
Not necessarily. The decision depends on the property's specific risk, insurance costs, condition, location, price, and your comfort with the potential expenses. The important thing is to understand the risks before purchasing.
Thinking about buying?
Let's talk through your numbers first.
A 30-minute call covers what you can afford comfortably, what taxes and insurance really cost in the town you're looking at, and which loan programs fit you. You work directly with Alexander from the first call to closing.
Schedule a buyer callEnglish or Spanish · Call or text 401-426-4857 · Contact form
196 Waterman St, Providence, RI 02906 · C: (401) 426-4857 · O: (401) 351-2017 · [email protected] · alexparmenidez.realtor
Check out this article next
¿Qué Deben Saber los Compradores Sobre las Zonas de Inundación Antes de Comprar una Casa?
Las zonas de inundación pueden afectar mucho más que las áreas donde podría llegar el agua
Read Article