3 Mistakes That Almost Blew Up a 3-Family Investment Purchase in Rhode Island (Julio's Real Story)
Quick Answer
Published September 2026 · Central Falls and Pawtucket, RI
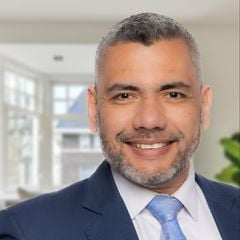
What are the most common mistakes when buying an investment property in Rhode Island? Relying on a single lender, not quoting investment-property insurance before you offer, and not requiring tenant security deposits in writing. All three happened to Julio Palacios in one purchase, and all three are avoidable. How do you buy without regretting it? You buy on numbers, not emotion. Julio Palacios had just finished paying off the home he lives in, decided to invest in a 3-family close to his daily life in the Central Falls–Pawtucket area, and closed after months of touring homes, losing offers, and solving three surprises: a lender who did not deliver what was promised, insurance quotes nearly double what he expected, and a tenant security deposit that never made it to closing.
- Rent has to cover the mortgage from month one. Julio passed on cheaper homes because they needed months of repairs before they could rent. For you: calculate how long you go without income and whether your budget can carry it.
- One lender is a risk. The promised rate was not the offered rate. For you: have two lenders competing from the start, not once you are under contract.
- Investment property insurance costs more than your home's. Julio's quotes came in at nearly double. For you: get insurance quotes before you make the offer, not after.
- Tenant deposits must transfer at closing. A communication breakdown left the new owner without the deposit and with frustrated tenants. For you: require deposit amounts and their transfer in writing.
Full interview with Julio Palacios (in Spanish). A complete English transcript is at the end of this article. Watch on YouTube → · Watch the vertical version on TikTok →
Why Did Julio Decide to Buy a Second Home as an Investment?
This was not an impulse purchase. Julio finished paying off the mortgage on the home he lives in, and only then started thinking about putting his money into another property. In his words, the benefit is clear: someone else pays the mortgage, the rent covers the taxes, the home gains value over time, and there is still income left over each month.
There are many investment vehicles. Julio chose a multifamily because he wanted to keep the rental income and grow his net worth step by step, with something he can see, touch, and control.
What this changes for you: if you are considering an investment property, start with your own financial position. Julio bought from a position of strength, with no mortgage on his residence and reserve funds in place. That let him say no to several homes without pressure.
Why Rhode Island, and Why Close to Home?
Julio could have bought in Massachusetts or Connecticut. He chose Rhode Island, and specifically the Central Falls–Pawtucket area, for a practical reason: control. He will manage the property himself, maybe with some help, but he wants to be there in minutes if there is an emergency, not drive hundreds of miles.
We met at a 3-family in Woonsocket. After seeing it together, the conversation shifted: not "I want to buy because I want to invest," but "where does this make sense for my life?" That distinction, between buying on desire and buying with structure, is the difference between an investment and a headache.
What this changes for you: define your driving radius before you start searching. A property you cannot attend to personally will cost you in management, in time, or both.
If you want to see how these two markets are moving before you decide, the detail is on the site: my Pawtucket guide and Central Falls guide cover prices, taxes, and housing type for each city; my appraiser-style CMA for a Pawtucket investment property shows exactly how I run the numbers Julio and I ran together; and the bilingual guide to buying in Central Falls explains why that city's median is really a multifamily number.
The Frustration of Seeing So Many Homes
Julio said it plainly: the hardest part was the frustration. Seeing so many homes, in so many places, and having one after another not work out.
The pattern repeated. The house looked perfect, the price seemed fine, and then he sat down to run the numbers and they did not add up. Sometimes it was the price against expected rent. Other times it was time: a lower-priced home that needed work and at least six months before it would produce rent. For Julio, on his second purchase, that wait was not acceptable. He needed a property that generated income immediately.
And then there were the lost offers. He would submit, and someone else would take it.
I compare it to batting: you swing, you miss, you keep swinging until the home run comes. The more you go out, the more numbers you run, the closer you are to the one that works. Julio persisted, and today he says he feels at peace because he made every effort to buy a property that gives him the numbers he wanted.
What this changes for you: every home you pass on with numbers is a lesson, not a loss. Have your formula ready (price, rent, expenses, time to first rent) and apply it the same way to every house.
Challenge 1: The Lender Who Did Not Deliver
Julio had a budget and a single bank. He trusted that person to give him a good rate based on his credit. It did not happen: the rate offered was much higher than he expected.
That is when Patricia Vargas stepped in. We negotiated, and Julio got what he wanted, the way he wanted it. But the scare was real, and it came under contract, when the clock was already running.
What this changes for you: never rely on a lender's verbal promise. Until you have a written Loan Estimate, you have nothing. Have a second lender comparing before you make the offer. In my experience, this is one of the things I see go wrong most often on investment purchases.
Challenge 2: Insurance at Nearly Double
Julio pays under $2,000 a year for the insurance on his home and expected something similar. The surprise: for an investment property, the quotes came in at nearly double. He shopped several places, and the number was still too high.
We worked on it together, quoted more options, and landed favorable coverage that fit within the numbers. But it was another fight that was not in the plan.
What this changes for you: insurance on a non-owner-occupied property almost always costs more than on your primary residence. Get quotes before you make the offer and build them into your cash-flow calculation. If insurance breaks the numbers, better to know before you sign.
Challenge 3: The Tenant Security Deposit
This is the lesson I most want you to remember. When we went to take possession, we discovered the previous owner had collected a security deposit from the tenants, but there was a language barrier and a dispute over that deposit. The result: the new owner did not receive the deposit, the tenants had expectations that were never made clear, and they started shooting the messenger, which was Julio.
Julio handled the conversation with the tenants transparently: this is what we have, this is what I received, here are my receipts. But the frustration showed, and it was something that should have been cleared up with the previous owner before closing.
What this changes for you: when you buy a property with tenants in place, require in writing (in the purchase and sale agreement) the amount of each security deposit, that they transfer at closing, and copies of the leases. And know why it matters so much: Rhode Island's security deposit statute (R.I. Gen. Laws § 34-18-19) says in subsection (g) that when a landlord transfers their interest in the premises, whoever holds that interest when the tenancy ends is bound by the same section. In plain terms: the new owner is the one who has to return the deposit when the tenant leaves, even if the previous owner kept it. The same statute caps the deposit at one month's rent and requires it to be returned within 20 days after the tenant delivers possession and provides a forwarding address. This is not legal advice; confirm it with your closing attorney before you sign. That is why it is called a closing: it is the moment to close the chapter with everything clear, so there are no surprises.
Buy the Potential, Not the Defects
Julio has a clear philosophy: if he focuses on what is wrong with a house, he never buys anything. He focuses on the potential. He knows he will have to put money into each unit to bring them to the standard he wants and to market level; exactly how much will be clear once the improvements are scoped.
Why invest in units that are already rented? Because you cannot charge market rent for an apartment that is not at market standard. As Julio puts it, nobody wants to feel taken advantage of. A tenant who feels they are getting fair value stays, pays on time, and takes care of the property.
What this changes for you: budget improvements from the start, unit by unit, and treat them as part of the purchase price, not a surprise expense.
What I Saw From My Side of the Table
After 14 years helping buyers across Rhode Island, Massachusetts, and Connecticut, these are the four things Julio did right, or nearly got wrong, that I would tell the next investor:
He paid off his home first. He bought without pressure, with reserves to cover a vacant unit without a problem. That let him buy on numbers, not emotion.
He walked away when the numbers did not work. He lost offers and passed on homes, but he never bought on impulse. The one he bought produces income from month one.
He almost relied on a single lender. The verbal promise did not hold. Having Patricia as a backup saved the closing.
He learned the deposit lesson. With existing tenants, deposits and leases must be in writing and transfer at closing. Period.
Next Steps If You Are Thinking About Your First Investment Property
- Check your foundation: is your residence stable, and do you have reserves for 2 to 3 months of mortgage without rent?
- Define your driving radius: how far are you willing to go to handle an emergency?
- Build your formula: price, current rent, expenses (taxes, investment insurance, maintenance), and time to first rent.
- Get pre-approvals from two lenders, with written Loan Estimates.
- Get investment-property insurance quotes before you offer.
- If the house has tenants, require leases, deposit amounts, and their transfer in the contract.
- Call me. We tour together, we run the numbers together, and I tell you the truth even when it is not what you want to hear.
Frequently Asked Questions
How much money do I need to buy an investment property in Rhode Island?
It depends on the financing. A conventional investment loan usually requires a larger down payment than a primary residence, and you need reserves to cover vacancies and repairs. Julio bought after paying off his residence and with enough funds to carry a vacant unit. Confirm exact requirements with your lender.
Why does insurance on an investment property cost more?
Insurers treat a non-owner-occupied property as higher risk and price it accordingly. Julio's quotes came in at nearly double what he pays on his residence. Get several quotes before you make an offer and build them into your numbers.
What happens to security deposits when I buy a home with tenants?
Deposits the tenants paid should transfer to the new owner at closing, and the amounts should be in writing in the purchase and sale agreement. Under Rhode Island law (R.I. Gen. Laws § 34-18-19(g)), whoever owns the property when the tenancy ends is bound to return the deposit, even if the previous owner never transferred it. If it is not settled before closing, you can end up refunding money you never received. Confirm the details with your closing attorney.
Should I buy a home that needs repairs or one that already produces rent?
It depends on your situation. Julio, on his second purchase, needed immediate income and passed on cheaper homes that required six months of work. If you have the time and funds to renovate, a home with potential can deliver a better return. If you need rent to cover the mortgage from month one, buy something rent-ready.
How do I avoid losing offers in the Rhode Island market?
Have your written pre-approval, your numbers, and your decision made before you see the house. Julio lost offers before landing the right one. Persistence with a clear formula is what works; impulse does not.
Let's Talk About Your First Investment Property
Julio summed it up better than I could: the help was invaluable, and this is only the beginning. We are already talking about the next property. That is how a business grows, with transparency, with the truth even when it stings, and with families who buy calmly and without pressure. If you are thinking about your first investment property in Rhode Island, Massachusetts, or Connecticut, call or text me at 401-426-4857. We can talk in English or Spanish, and we run the numbers together.
Full video transcript (English translation)
Transcript edited for clarity and translated from the original Spanish. Interview recorded in the Central Falls–Pawtucket area of Rhode Island, September 2026.
Alex: Hi everyone, happy day. Thank you for watching this video. We're here today with Julio Palacios, and we just closed. Congratulations, Julio. But rather than talk about the closing, I'd like us to talk, as we say in Colombia, with nothing held back. What motivated you to buy? This is your second home, an investment. What was the motivation?
Julio: The peace of mind that comes with owning an investment property. You're investing in something not just for now, but for the future. You're securing your money, the value of the house will go up, and you're collecting rent: someone is paying you rent, paying your mortgage, and the house is yours. You get all of that through the investment.
Alex: So what I'm hearing is that the benefit was, above all, a return on investment. There are different investment vehicles, but you decided to go into a multifamily to keep the rental income and grow your net worth step by step.
Julio: Exactly.
Alex: Why Rhode Island? Why did you buy here and not in Massachusetts or Connecticut?
Julio: Because I need to have control of the property. It needs maintenance; it has three apartments, and I'm going to be the one in charge. Maybe I'll look for some help from someone else, but I need to be in control.
Alex: Close to where you live, so if there's an emergency you can get there right away instead of traveling thousands of miles. Very good observation: close to the circle where you live. Now, how long had you been thinking about buying your second home?
Julio: I finished paying off the house I live in, and then I started thinking about investing my money in another house. Once it was paid off, I knew I was free of that mortgage and could focus. Since the house I live in is a two-family, I have the rental income, which pays the property taxes and still leaves me something extra. On top of the job I have, I'm comfortable paying the mortgage I took on now.
Alex: Because in the end it all has to be numbers. It's a business decision more than an emotional one. One plus one is two, not twenty-five. Know your budget.
Julio: Exactly. You have to have funds to make sure that if someone moves out, there's no problem: you can cover it without difficulty, so your investment stays healthy.
Alex: Rhode Island, proximity, numbers, investment. Whether you're a first-time buyer or an investor, it's very important to know the numbers and how far you can go. That all sounds nice; now let's talk about the other side of the coin. What were the hard moments of this transaction, the challenges you ran into, so people know how to prepare?
Julio: More than anything, what I had was frustration: from seeing so many houses, from going to so many places.
Alex: Let's expand on that. What was it about those houses that didn't work for you?
Julio: Sometimes everything looked perfect, and then, when I started running the numbers properly, they didn't add up. The price could be fine, everything could look fine, but once you start doing the math you say: no. Or the time it would take to get it ready to rent. All of that has to be taken into account. And I especially had to consider it because this is the second house I'm buying: I need a house that produces income immediately. I could have bought another house at a lower price, but I would have had to put money into it and wait at least six months before starting to collect rent. For me that was very important. The other thing was that sometimes I'd put in an offer and someone else would come and take it.
Alex: And that was part of the exercise. As they say: you did the homework, but you didn't pass, so you have to do it again.
Julio: But in the end I know it was a good investment, a good purchase, that is going to start producing immediately from now on.
Alex: That resonates with me. When we were looking at houses it was like baseball: you swing, you miss, but you keep swinging until the home run comes. It's a numbers game: the more you go out, the more you look at the numbers, if you hit it, you did it; if not, keep going.
Julio: It's persisting and persisting until the opportunity comes. It's worth waiting and being persistent, and when it comes, you know it's going to be something like how I feel now: at peace. I know I made every effort to buy a property that will give me the numbers I expect and will work perfectly for me.
Alex: One of the frustrations was touring houses. But once you were under contract, what was the frustration? What was the fight?
Julio: I only had one budget, but I also only had one lender, one bank that was going to lend to me. I was confident that person would give me a good rate based on my credit, but that's not how it went. It was a surprise to me; in a way I think what they did wasn't right, because they were offering me a very high interest rate.
Alex: "That's what there is."
Julio: That's what there is. So I said: I have other options, and I asked for your help. That's when Patricia came in.
Alex: Yes, Patricia Vargas.
Julio: We started negotiating and it was done the way I wanted. Yes, it had to be negotiated, but thanks to them I got what I wanted. The other thing was the home insurance. The insurance I pay now doesn't exceed $2,000, and my surprise was finding out that for an investment it was almost double. That's when I really shopped around and asked for quotes, and the number didn't sound right: it was too high. Once again I got Alex's help, which has been invaluable in making this happen, and thanks to that we got very favorable insurance that is now completely fine.
Alex: Perfect. So the insurance is within the numbers, and with the fight alongside Patricia, the loan is too. Those were the two challenges on your side. Any other challenge you can share with the people watching, regarding the house?
Julio: My expectation has always been that I can improve a house. If I focus on what's wrong with it, I don't buy it. But the potential the house has is big; I focus on the potential. I'm aware that I have to invest in each apartment so it's the way I want it and up to the standard to rent it.
Alex: Exactly. You invest because you can't charge market rent for an apartment that isn't at market level. You have to provide a service people are willing to pay for, because, like any human being, nobody wants to feel taken advantage of. And there's another situation, especially for the people watching this video: the tenants. The previous owner had collected a deposit, but there was a language barrier, and when we went to take possession of the house, the tenants had a dispute about the deposit. It's very important that, when you're selling a house with tenants, that deposit is transferable and the amount is clear, so there are no surprises later. A small mistake slipped through: the previous owner keeps the deposit, the new owner has no idea, and they start shooting the messenger.
Julio: Unfortunately, the expectations weren't clear for them. But I know I have the receipt to show them what I received. If the previous owner didn't do their due diligence, that's part of buying a house: you have to receive the deposit.
Alex: This is advice for anyone who wants to buy a house, so you're not caught off guard. That's what we lived today, and it was good to have the conversation with the tenant. Obviously the frustration showed, but it was something that had to be discussed with the previous owner.
Julio: Exactly. That's something very important that had to be cleared up, because the closing is the moment where everything has to be put in place and fully clarified, so there are no surprises.
Alex: That's why it's called a closing: let's close the chapter and have everything clear. Now, throughout this whole process, how would you recommend this service to people? We met at a three-family house in Woonsocket.
Julio: Exactly, a massively large house. I was looking at properties in Woonsocket, and then I said: no, I'm not going to move completely away from my area.
Alex: We come back to what we talked about at the beginning: something close, manageable. Because it's not the same to go buy because I want to buy and make money, as it is to look at what's out there in a structured way. That's what we did: can we here? can we there? It has to be done that way, because otherwise you buy on impulse, and you may buy something that won't be good as an investment. So what did you think of this buying service?
Julio: Honestly, without your help I couldn't have done it. Many of the things I needed help with, you made easier, and that has been very important to me. I thank you. I bought my other house a long time ago, and you forget so many things you have to do. I'm really pleased. We're already talking about other deals in the future, and that tells you everything.
Alex: For me the most important thing is transparency. Within that transparency you become like friends, because you tell it like it is. It's not a transaction and done; it's: what's the real situation? Because the idea is to grow. Everything is based on a transparent conversation, because in the end nobody wants to feel taken advantage of.
Julio: Your business is real. I've always said you have to do your job as well as possible, because that's your present and your future. If I do excellent work, I'll have an excellent future, because people will come, they'll refer: "oh, there's Alex, here's his card, work with him."
Alex: That's how the business grows, and that's how more families get the chance to buy consciously, without rushing, without feeling pressured. Everything has to flow.
Julio: Exactly. You want something where you made the decision, because the one carrying that commitment for 30 years, the one who signs, is you. But Alex's help was excellent. I really appreciate it. I can't say anything but thank you, and thank God this is done, that it's a reality. There will be more deals in the future. This is only the beginning.
Alex: Well, everyone, I hope this video was educational. Learn from Julio: first of all, look at the numbers, because in the end that's what matters. Thanks for watching. See you next time. Julio, thank you.
Julio: Thank you, Alex.
Check out this article next
3 errores que casi arruinan la compra de una casa de 3 familias en Rhode Island (la historia real de Julio)
Un prestamista que no cumplió, un seguro al doble y un depósito de inquilinos que nunca llegó al cierre. Así casi se cae la compra…
Read ArticleLooking at a 2–4 family?
Run the real numbers before you offer.
Actual versus market rents, the FHA self-sufficiency test, taxes, insurance and financing. Alexander has closed more than 275 transactions, many of them multifamily in Providence, Pawtucket and Central Falls, and will tell you plainly whether a property works.
Schedule a multifamily callEnglish or Spanish · Call or text 401-426-4857 · Contact form
196 Waterman St, Providence, RI 02906 · C: (401) 426-4857 · O: (401) 351-2017 · [email protected] · alexparmenidez.realtor